Financial Information as of September 30th 2026
13 November 2026
Generali continues to deliver strong results thanks to all business segments
- GWP grew to € 76.5 billion (+4.5%) driven by both P&C (+6.3%) and Life (+3.5%)
- Continued strong Life net inflows of € 11.7 billion (+13.6%). New Business Value increased substantially to € 2.6 billion (+12.7%)
- Combined Ratio was 92.8% (+0.5 p.p.); Undiscounted Combined Ratio was 95.1% (+0.9 p.p.), reflecting higher nat cat and man-made claims
- Excellent growth in operating result to € 6.4 billion (+8.5%) driven by all business segments
- Asset & Wealth Management operating result increased very strongly (+23.2%) exceeding € 1 billion, thanks to the robust underlying performance of both businesses
- Adjusted net result increased significantly to € 3.7 billion (+12.0%), while adjusted EPS rose to € 2.43 (+12.4%)
- Group’s total AUM reached € 934 billion (+3.8% FY2025), of which 44% third-party
- Very solid capital position maintained with Solvency Ratio at 211% (219% FY2025) supported by sound capital generation
Generali Group CFO, Cristiano Borean, said: “The excellent results for the first nine months reflect the successful implementation of our strategic plan, continuing the Group’s strong growth supported by all business segments. In Insurance, Life continued to deliver best-in-class net inflows, with new business value growth and strong profitability. P&C demonstrated resilient underlying performance despite over one billion Euro higher impact from natural catastrophe and large man-made events. Asset & Wealth Management continued to produce significant result growth. This performance demonstrates the strength of our diversified business model, the quality and resilience of our earnings, and our disciplined approach to capital management. This further reinforces the Group’s competitive position and provides us with great confidence to exceed all the targets of our ‘Lifetime Partner 27: Driving Excellence’ strategic plan.”
Executive summary
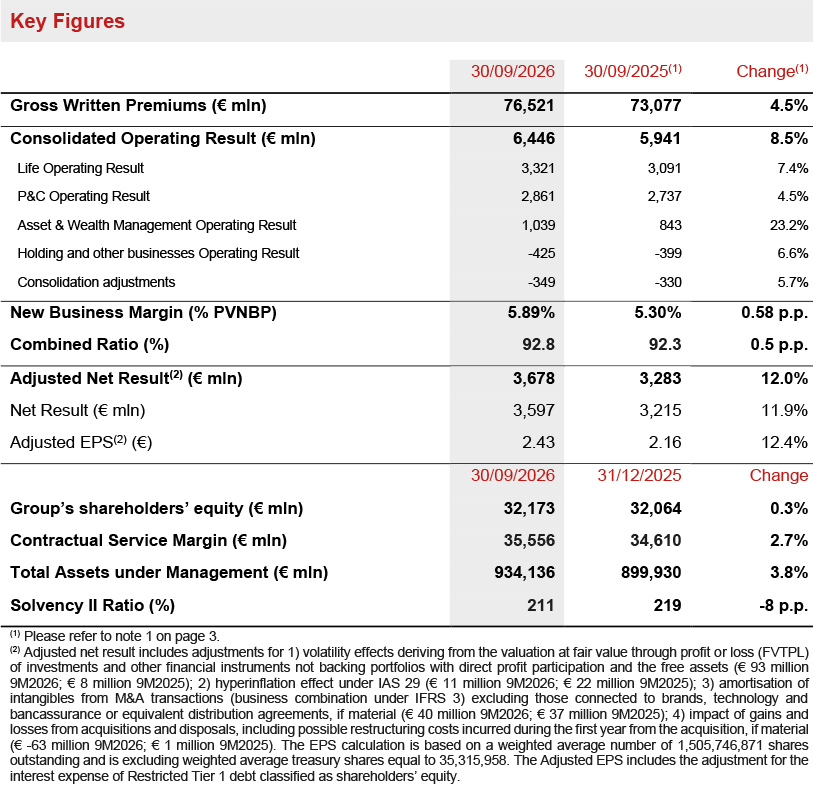
Milan – At a meeting chaired by Andrea Sironi, the Generali Board of Directors approved the Financial Information of the Generali Group as at 30 September 20261.
Gross written premiums (GWP) grew to € 76.5 billion (+4.5%), driven by both P&C (+6.3%) and Life (+3.5%).
Life net inflows remained strong at € 11.7 billion (+13.6%). This was thanks to a positive contribution from all business lines.
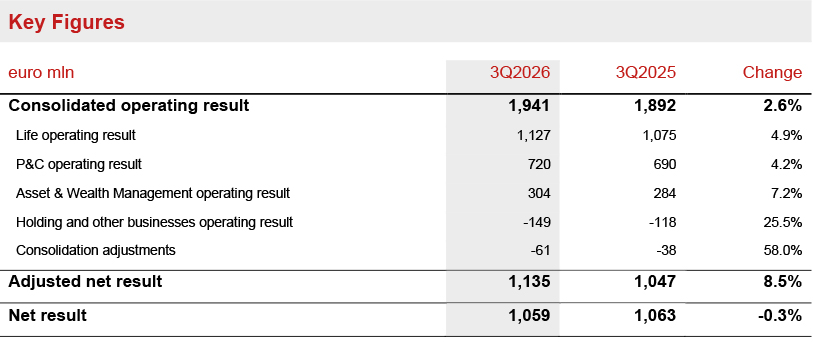
Operating result grew strongly to € 6,446 million (+8.5%), thanks to all business segments.
Life operating result increased to € 3,321 million (+7.4%). New Business Value rose substantially to € 2,563 million (+12.7%), supported by improved profitability and higher volumes.
P&C operating result increased to € 2,861 million (+4.5%), with the Combined Ratio at 92.8% (+0.5 p.p.) and the undiscounted Combined Ratio at 95.1% (+0.9 p.p.), reflecting the higher impact of natural catastrophe and man-made losses.
Asset & Wealth Management operating result increased strongly to € 1,039 million (+23.2%), driven by both Asset Management at € 482 million (+12.3%) and the Banca Generali group at € 557 million (+34.4%), the latter also benefiting from higher performance fees.
Holding and other businesses operating result was € -425 million (€ -399 million 9M2025).
Adjusted net result2 increased strongly to € 3,678 million (+12.0%), underpinned by solid operating performance. Net result rose to € 3,597 million (+11.9%).
Adjusted EPS3 rose significantly to € 2.43 (+12.4%).
Group’s shareholders' equity increased to € 32.2 billion (+0.3%), mainly reflecting the net result for the period, partly offset by the 2025 dividend payment and the repurchase of own shares.
Contractual Service Margin (CSM) rose to € 35.6 billion (+2.7% compared with FY2025).
The Group’s Total Assets Under Management grew to € 934 billion (+3.8% compared with FY2025).
The Group confirms its solid capital position with the Solvency Ratio at 211% (219% FY2025), resulting from € 52.3 billion of Eligible Own Funds and € 24.8 billion of Solvency Capital Requirement.
The change primarily reflects the negative effect of market and non-economic variances, as well as the end of the subordinated bond grandfathering regime and capital movements stemming from the dividend for the period and the € 500 million share buy-back programme, net of the subordinated debt operations. These factors were only partially offset by the strong contribution from normalised capital generation supported by all business segments despite higher nat cat losses. The normalised capital generation also reflected the share buy-back for the Long-Term Incentive Plan (LTIP) executed in the first quarter.
Life
- Very strong Life net inflows at € 11.7 billion (+13.6%)
- Operating result rose to € 3.3 billion (+7.4%)
- New Business Margin was 5.89% (+0.58 p.p.); New Business Value grew substantially to € 2,563 million (+12.7%)
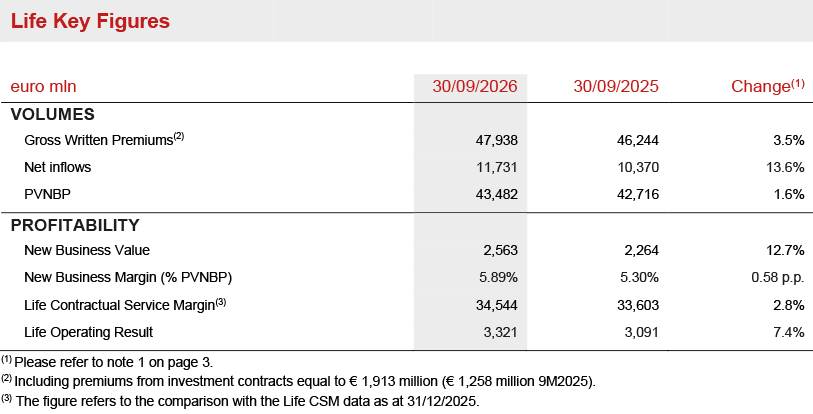
Life gross written premiums grew to € 47,938 million (+3.5%) notwithstanding the comparison with a strong 9M2025, during which extraordinary new production was recorded in Asia, especially in 1Q2025 and 3Q2025. All three lines of business posted consistent growth with traditional savings growing 5.9%, protection & health by 2.3% and hybrid & unit-linked by 2.6%.
Life Net inflows were very strong at € 11,731 million (+13.6%), also reflecting lower surrenders. Growth was mainly driven by traditional savings, which rose to € 3,319 million (+59.8%), led by Asia and Germany. Hybrid & unit-linked net inflows increased to € 4,922 million (+5.3%), thanks to France, while protection & health net inflows were € 3,490 million (-2.1%).
New business volumes (expressed in terms of present value of new business premiums - PVNBP) grew to € 43.5 billion (+1.6%), mainly thanks to the solid production in Asia (+14.7%) and France (+9.1%). In terms of business lines, traditional savings was stable (+0.3%), thanks to solid production in China and Germany, partially offset by a slowdown in Italy, reflecting the country’s focus on higher margin new production. Hybrid and unit-linked increased (+4.3%), supported by France and Italy. Protection and health slightly decreased (-2.6%) mainly reflecting lower contribution of the accepted collective business in France.
New Business Value (NBV) increased substantially to € 2,563 million (+12.7%) supported by overall improved profitability. The New Business Margin on PVNBP (NBM) expanded to 5.89% (+0.58 p.p.), mainly thanks to the positive impact of a more favourable product mix and features, as well as higher interest rates.
Life Contractual Service Margin (Life CSM) increased to € 34.5 billion (€ 33.6 billion FY2025). The positive development was mostly driven by the contribution of the Life New Business CSM of € 2,420 million, and an expected return of € 1,149 million, which more than offset the Life CSM release of € 2,534 million. The latter accounted for around 76% of the Life operating result, which increased to € 3,321 million (€ 3,091 million 9M2025). The operating insurance service result increased to € 2,626 million (€ 2,443 million 9M2025), while the operating investment result reached € 695 million (€ 647 million 9M2025).
P&C
- Premiums increased to € 28.6 billion (+6.3%)
- Operating result grew to € 2,861 million (+4.5%)
- Combined Ratio at 92.8% (+0.5 p.p.) and Undiscounted Combined Ratio at 95.1% (+0.9 p.p.) both reflecting € 1.1 billion higher nat cat and large man-made events
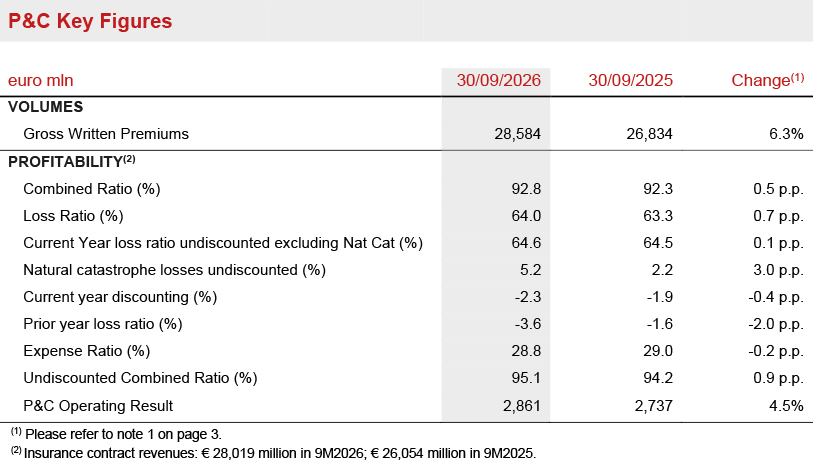
P&C gross written premiums grew to € 28.6 billion (+6.3%) thanks to the performance of both business lines. Non-motor achieved widespread growth (+5.2%) across all main geographies. The motor line rose by 5.0% with particularly positive performances recorded in Germany and CEE. Excluding the contribution from Argentina, motor line premiums increased by 3.7%. Redion premiums increased by 14.5% driven mainly by the US travel business and France.
Combined Ratio was 92.8% (92.3% 9M2025). Loss ratio was impacted by large events with € 1.47 billion of nat cat losses, accounting for 5.2% of Combined Ratio (2.2% 9M2025), and € 323 million of man-made losses, accounting for 1.2% of Combined Ratio (0.5% 9M2025). This more than offset the higher benefit from discounting at -2.3% (-1.9% 9M2025) and from the prior year loss ratio at -3.6% (-1.6% 9M2025).
Undiscounted current year loss ratio excluding nat cat and man-made improved by 60 basis points to 63.5% (64.0% 9M2025). Expense ratio improved to 28.8% (29.0% 9M2025) thanks to lower administrative and other expenses, driven by both recurring and one-off improvements. Expense ratio excluding the contribution of Redion Assistance & Insurance was 28.3% (28.6% 9M2025).
Undiscounted combined ratio was 95.1% (94.2% 9M2025).
Operating result grew to € 2,861 million (€ 2,737 million 9M2025).
Operating insurance service result was stable at € 2,008 million (€ 2,001 million 9M2025), despite the fact that 9M2026 recorded € 1,082 million more nat cat and man-made losses compared to 9M2025. This result was achieved thanks to the improvement in the underlying technical performance excluding large losses and the higher benefit from current year discounting of € 637 million (€ 486 million 9M2025), as well as a more positive prior year development.
Operating investment result improved to € 853 million (€ 736 million 9M2025), reflecting a € 121 million increase in the operating investment income to € 1,345 million, and stable insurance finance expenses of € -492 million (€ -488 million 9M2025). The increase in the operating investment income was achieved thanks to larger volumes and reinvestment yields higher than the maturing coupons, and despite a lower contribution from private equity dividends.
Asset & Wealth Management
- Asset & Wealth Management operating result increased significantly to € 1,039 million (+23.2%)
- Asset Management operating result rose notably to € 482 million (+12.3%)
- Banca Generali group operating result grew strongly to € 557 million (+34.4%)
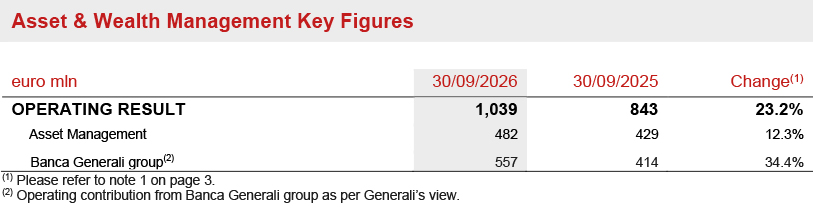
Asset Management operating result grew to € 482 million (+12.3%), driven by higher average AUM and improved fee margins.
Operating revenues increased to € 1,198 million (+11.7%), of which € 555 million from third-party assets, supported by higher average AUM and a more favourable asset mix. Operating expenses rose 11.4%, also due to higher personnel costs. Both revenues and expenses reflect the consolidation of MGG Investments.
The operating result of the Banca Generali group rose strongly to € 557 million (+34.4%) also thanks to higher performance fees amounting to € 146 million (€ 72 million 9M2025). Total net inflows at Banca Generali in 9M2026 were € 6.3 billion.
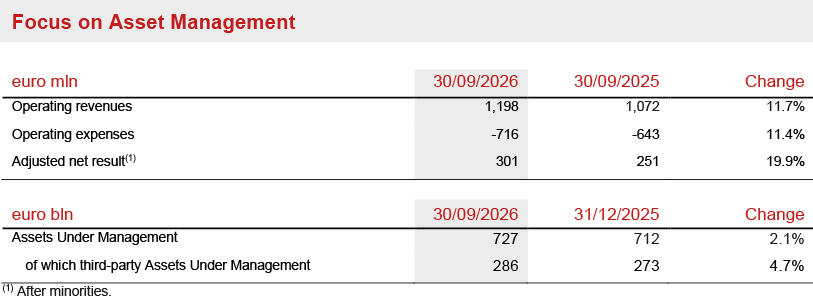
Asset Management adjusted net result increased to € 301 million (+19.9%), mainly thanks to the higher operating result and lower non-operating expenses for integration and M&A costs.
AUM pertaining to the Asset Management companies reached € 727 billion, up 2.1% compared with FY2025, supported by positive net flows and favourable FX effects, which more than offset negative market effects.
Third-party AUM reached € 286 billion, up 4.7% compared with FY2025, reflecting positive net flows of € 8.8 billion in the first nine months of 2026 as well as favourable FX effects, which also more than offset negative market effects.
Holding and other business
- Operating result stood at € -425 million (€ -399 million 9M2025)
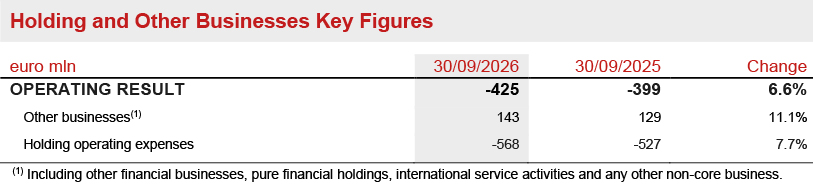
Holding and other businesses operating result was € -425 million (€ -399 million 9M2025).
Operating result of Other businesses increased to € 143 million (€ 129 million 9M2025, negatively impacted by a one-off exit tax in 1Q2025). Holding operating expenses grew by 7.7% to € -568 million (€ -527 million 9M2025), also due to higher costs reallocated to the Holding segment.
Outlook
Global macroeconomic activity has remained resilient despite persistent geopolitical tensions in the Middle East and the significant rise in bond yields. In the Euro Area, growth positively surprised in the third quarter, although momentum is expected to moderate around the turn of the year given recent weaknesses in confidence indicators and tighter financing conditions. Overall, the economy in the Euro area is expected to expand by around 1% in 2026 and 1.2% in 2027. The election cycle in late 2026 and 2027 may also carry some risks, with fiscal and political uncertainty already reflected in the widening of some European sovereign spreads. In the US, economic activity has proven to be more robust, supported by resilient consumption and strong capital expenditure, particularly thanks to continued investment in technology and information-processing equipment. At the same time, the scale and financing of AI-related investments are coming under increasing scrutiny. US growth is expected to stay above trend this year and next.
Inflation continues to be a source of uncertainty on both sides of the Atlantic. In the Euro Area, headline inflation rose markedly in September, partly reflecting higher energy costs, and is expected to ease only after the first quarter of 2027. In the US, underlying price pressures have remained persistent, with core PCE inflation staying above 3%. Against this backdrop, central banks are likely to maintain a cautious approach. The European Central Bank and the Federal Reserve both kept policy rates unchanged at their October meetings, while retaining a tightening bias in response to persistent inflationary pressures. Two additional 25 basis point increases are expected by each central bank, in December and in the first quarter of 2027.
More than halfway through the Lifetime Partner 27: Driving Excellence strategic plan, Generali continues to execute its strategic priorities successfully, with underlying market trends staying in line with the plan’s assumptions and supporting continued business development. In addition, the rapid acceleration of AI adoption is creating new opportunities to enhance customer experience, productivity and innovation, reinforcing the importance of execution excellence and adaptability. The Group also remains deeply committed to the strategic plan’s people and sustainability foundations, continuing to invest in skills, leadership, culture and sustainable value creation as key enablers of long-term success.
In Life, capitalising on Generali’s broad global customer base and strong distribution footprint, Generali’s focus remains on improving technical proficiency and on simplification, offering updated and integrated solutions to adapt to evolving customer needs throughout their lifetime. The main areas of focus include protection and health products, as well as capital-light savings solutions, with the goal of becoming the partner of choice for each customer. The Group’s hybrid and unit-linked offers continue to be a priority to address growing customer needs for financial security with the objective to become the go-to partner for retirement and savings.
In P&C, the Group’s objective is to maximise profitable growth - with a focus on non-motor lines - across the insurance markets where it operates, strengthening its position and offering, especially in countries with high growth potential. The Group confirms and reinforces its flexible approach to tariff adjustments, also considering the increasing frequency and severity of Nat Cat events. The non-motor offer will continue to be enhanced through the addition of modular solutions designed to address specific customer needs. Generali will continue to increase its focus on developing insurance solutions related to the environment and climate change. The Group Climate Hub continues to support the delivery of these efforts with the enhancement of methodologies and approaches to understand and manage physical risks.
With reference to investment policy, the Group continues to pursue an asset allocation strategy aimed at ensuring consistency with policyholder liabilities and improving risk-adjusted returns with a focus on increasing current income. Investments in private and real assets will continue to be pursued gradually to enhance portfolio diversification and capture opportunities, with a prudent approach taking into account the lower liquidity and higher complexity of these instruments. In real estate, the Group pursues a policy of geographical and sectorial diversification, closely monitoring and evaluating market opportunities and asset quality.
Within Asset & Wealth Management, Asset Management continues to expand its product offering, including entry to the active ETF segment, while maintaining a strong focus on private and real assets, strengthening its distribution network and further improving the quality of service provided to clients. In Wealth Management, Banca Generali group continues to pursue its organic growth strategy, while also leveraging the opportunities arising from the integration of Intermonte, the partnership with Alleanza in the insurbanking segment, and the adoption of AI as a key driver of innovation and productivity.
The Group remains committed to delivering a solid level of shareholder remuneration.
Through its Lifetime Partner 27: Driving Excellence strategic plan – the Group is committed to delivering ambitious 2025-2027 growth targets:
- strong earnings growth: 8-10% EPS CAGR4;
- solid cash generation: > € 11 billion Cumulative Net Holding Cash Flow5;
- increasing dividend per share6: > 10% DPS CAGR7 with ratchet policy;
with a clear capital management framework with increased focus on shareholder returns:
- more than € 7 billion in cumulative dividends8 (2025-2027);
- committed to at least € 1.5 billion share buyback9 over the plan horizon;
- € 500 million buyback started on 10 August and completed in October 2026.
Significant events after September 30th 2026
On 1 October, Generali announced an agreement to acquire a c. 9.9% stake in Banco de Crédito Cooperativo (BCC), the holding entity of Grupo Cooperativo Cajamar, for € 150 million.
On 8 October, Generali announced the launch of We SHARE 3, the third edition of its employee share ownership plan, approved by the Shareholders’ Meeting of April 2026. Nearly 35,800 employees across 32 countries joined it.
On 20 October, the Board of Directors approved the evolution of the Group’s organisational structure, effective 2 November 2026.
On 23 October, the 2027 Generali Corporate Events Calendar was published.
Other significant events that occurred after the end of the period are available on the website.
***
Q&A conference call
The Direttore Generale - Group Deputy CEO, Giulio Terzariol, and the Group CFO, Cristiano Borean will host the Q&A session conference call for the consolidated results of the Generali Group as of 30 September 2026, which will be held on 13 November 2026, at 2:30 pm CET.
To follow the conference call, in a listen only mode, please dial +39 02 8020927.
***
The Manager in charge of preparing the company’s financial reports, Cristiano Borean, declares, pursuant to paragraph 2, article 154 bis of the Consolidated Law on Finance, that the accounting information in this press release corresponds to the documented results, books and accounting entries
Generali 3Q 2026 Results
1 Changes in premiums, Life net inflows and new business are presented on a like-for-like basis (i.e. assuming constant exchange rates and scope of consolidation). Changes in total AUM and the Solvency Ratio are calculated by comparing them with the corresponding figures at the end of the previous year. Amounts are rounded to one decimal place; consequently, the sum of the rounded amounts may not, in all cases, equal the rounded total. The same may apply to variances.
2 For definition of the adjusted net result, please refer to note 2 on page 2.
3 For definition of the adjusted EPS, please refer to note 2 on page 2.
4 3-year CAGR based on the Group’s adjusted EPS.
5 Expressed on cash basis.
6 Subject to all relevant approvals.
7 3-year CAGR with 2024 baseline at € 1.28 per share.
8 Subject to all relevant approvals.
9 Subject to all relevant approvals.